Showing posts with label carbon price. Show all posts

Monday, June 20, 2016

New OxCARRE Research: Stranded assets, the social cost of carbon, and directed technical change: Macroeconomic dynamics of optimal climate policy

New OxCARRE research from

Frederick van der Ploeg ([ox.ac.uk], OxCARRE) and Armon Rezai ([wu.ac.at], WU - Vienna University of Economics and Business)

Stranded assets, the social cost of carbon, and directed technical change: Macroeconomic dynamics of optimal climate policy

Abstract
The tractable general equilibrium model developed by Golosov et al. (2014), GHKT for short, is modified to allow for stock-dependent fossil fuel extraction costs and partial exhaustion of fossil fuel reserves, a negative impact of global warming on growth, mean reversion in climate damages, steady labour-augmenting technical progress, specific green technical progress driven by learning by doing, population growth, and a direct effect of the stock of atmospheric carbon on instantaneous welfare. We characterize the social optimum and derive simple rule for both the optimal carbon tax and the renewable energy subsidy, and characterize the optimal amount of untapped fossil fuel.
Available here [ox.ac.uk].

Thursday, January 28, 2016

New OxCARRE Research: Second-Best Renewable Subsidies to De-Carbonize the Economy: Commitment and the Green Paradox


A new OxCARRE research paper is available from

Armon Rezai (Vienna University of Economics and Business [wu.ac.at]) and
Frederick van der Ploeg (OxCarre, oxcarre.ox.ac.uk)

writing on

Second-Best Renewable Subsidies to De-Carbonize the Economy: Commitment and the Green Paradox
Abstract
Climate change must deal with two market failures: global warming and learning by doing in renewable use. The first-best policy consists of an aggressive renewables subsidy in the near term and a gradually rising and falling carbon tax. Given that global carbon taxes remain elusive, policy makers have to use a second-best subsidy. In case of credible commitment, the second-best subsidy is set higher than the social benefit of learning. It allows the transition time and peak warming close to first-best levels at the cost of higher fossil fuel use (weak Green Paradox). If policy makers cannot commit, the second-best subsidy is set to the social benefit of learning. It generates smaller weak Green Paradox effects, but the transition to the carbon-free takes longer and cumulative carbon emissions are higher. Under first-best and second best with pre-commitment peak warming is 2.1 - 2.3 °C, under second best without commitment 3.5°C, and without any policy temperature 5.1°C above pre-industrial levels. Not being able to commit yields a welfare loss of 95% of initial GDP compared to first best. Being able to commit brings this figure down to 7%.
Paper available here [oxcarre.ox.ac.uk] 

Monday, January 18, 2016

The Price of Oil and the Price of Carbon

OxCARRE associate Rabah Arezki and Maurice Obstfeld from the IMF, and also available on the IMFDirect blog here, write on

The Price of Oil and the Price of Carbon

By Rabah Arezki and Maurice Obstfeld

“The human influence on the climate system is clear and is evident from the increasing greenhouse gas concentrations in the atmosphere, positive radiative forcing, observed warming, and understanding of the climate system.”Intergovernmental Panel on Climate Change, Fifth Assessment Report

Fossil fuel prices are likely to stay “low for long.” Notwithstanding important recent progress in developing renewable fuel sources, low fossil fuel prices could discourage further innovation in and adoption of cleaner energy technologies. The result would be higher emissions of carbon dioxide and other greenhouse gases.

Policymakers should not allow low energy prices to derail the clean energy transition. Action to restore appropriate price incentives, notably through corrective carbon pricing, is urgently needed to lower the risk of irreversible and potentially devastating effects of climate change. That approach also offers fiscal benefits.

Low for long
Oil prices have dropped by over 60 percent since June 2014 (see Chart 1). A commonly held view in the oil industry is that “the best cure for low oil prices is low oil prices.” The reasoning behind this adage is that low oil prices discourage investment in new production capacity, eventually shifting the oil supply curve backward and bringing prices back up as existing oil fields—which can be tapped at relatively low marginal cost— are depleted. In fact, in line with past experience, capital expenditure in the oil sector has dropped sharply in many producing countries, including the United States. The dynamic adjustment to low oil prices may, however, be different this time around.
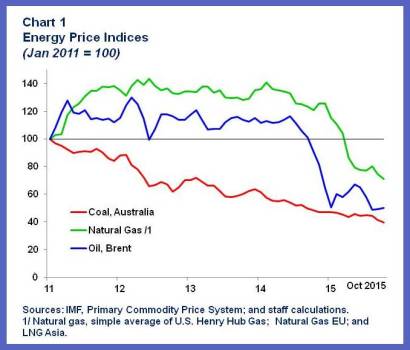


Oil prices are expected to remain lower for longer. The advent of shale oil production, made possible by hydraulic fracturing (“fracking”) and horizontal drilling technologies, has added about 4.2 million barrels per day to the crude oil market, contributing to a global supply glut. Shale oil will lead to shorter and more limited oil-price cycles. Indeed, shale requires a lower level of sunk costs than conventional oil, and the lag between first investment and production is much shorter. Furthermore, shale is still at a relatively early stage of its industry life cycle, where the scope for learning is substantial, as shown by production levels that have proven resilient thanks to phenomenal efficiency gains forced by the big drop in oil prices.

In addition, other factors are putting downward pressure on oil prices: change in the strategic behavior of the Organization of Petroleum Exporting Countries, the projected increase in Iranian exports, the scaling down of global demand (especially from emerging markets), the secular drop in petroleum consumption in the United States, and some displacement of oil by substitutes. These likely persistent forces, like the growth of shale, point to a “low for long” scenario, even after the supply legacy left by the high-price era of the 2000s has dissipated. Futures markets, which show only a modest recovery of prices to around $60 a barrel by 2019, support this view.

Natural gas and coal—also fossil fuels—have similarly seen price declines that look to be long-lived. Coal and natural gas are mainly inputs to electricity generation, whereas oil is used mostly to power transportation, yet the prices of all these energy sources are linked, including through oil-indexed contract prices. The North American shale gas boom has resulted in record low prices there. The recent discovery of the giant Zohr gas field off the Egyptian coast will eventually have repercussions on pricing in the Mediterranean region and Europe, and there is significant development potential in many other locales, notably Argentina. Coal prices also are low, owing to oversupply and the scaling down of demand, especially from China, which burns half of the world’s coal.


Renewables at risk

Technological innovations have unleashed the power of renewables such as wind, hydro, solar, and geothermal. Even Africa and the Middle East, home to economies that are heavily dependent on fossil fuel exports have enormous potential to develop renewables. For example, the United Arab Emirates has endorsed an ambitious target to draw 24 percent of its primary energy consumption from renewable sources by 2021.

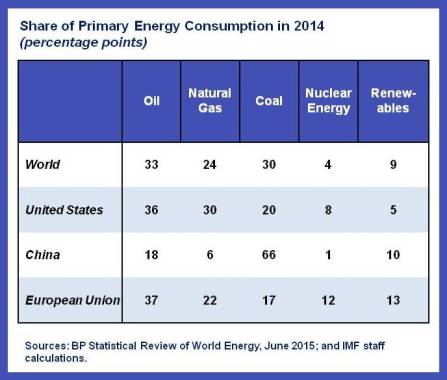
Progress in the development of renewables could be fragile, however, if fossil fuel prices remain low for long. Renewables account for only a small share of global primary energy consumption, which is still dominated by fossil fuels—30 percent each for coal and oil, 25 percent for natural gas (see Table). But renewable energy will have to displace fossil fuels to a much greater extent in the future to avoid unacceptable climate risks. Unfortunately, the current low prices for oil, gas, and coal may provide scant incentive for research to find even cheaper substitutes for those fuels. There is strong evidence that both innovation and adoption of cleaner technology are strongly encouraged by higher fossil fuel prices. The same is true for new technologies for mitigating fossil fuel emissions.
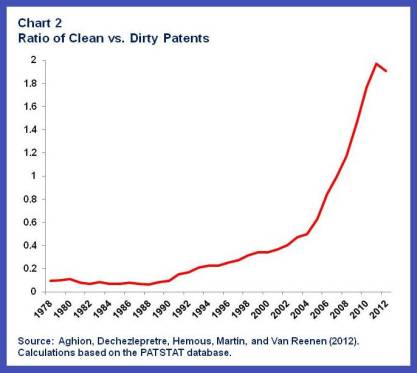


The current low fossil-fuel price environment will thus certainly delay the energy transition. That transition—from fossil fuel to clean energy sources—is not the first one. Earlier transitions were those from wood/biomass to coal in the eighteenth and nineteenth centuries, and from coal to petroleum in the nineteenth and twentieth centuries. One important lesson is that these transitions take a long time to complete. But this time we cannot wait.

We owe to electric lighting the fact that there are still whales in the sea. Unless renewables become cheap enough that substantial carbon deposits are left underground for a very long time, if not forever, the planet will likely be exposed to potentially catastrophic climate risks.

Some climate impacts may already be discernible. For example, the United Nations Children’s Fund estimates that some 11 million children in eastern and southern Africa face hunger, disease, and water shortages as a result of the strongest El Niño weather phenomenon in decades. Many scientists believe that El Niño events, caused by warming in the Pacific, are becoming more intense as a result of climate change.

Getting the price of carbon right

Nations from around the world have gathered in Paris for the United Nations Climate Change Conference, COP-21, with the goal of a universal and potentially legally binding agreement on reducing greenhouse gas emissions. We need very broad participation to address fully the global “tragedy of the commons” that results when countries fail to take into account the negative impact of their carbon emissions on the rest of the world. Moreover, free riding by non-participants, if sufficiently widespread, can undermine the political will to action of participating countries.

The nations participating at COP-21 are focusing on quantitative emissions-reduction commitments (the Intended Nationally Determined Contribution, or INDCs). Economic reasoning shows that the least expensive way for each country to implement its INDC is to put a price on carbon emissions. The reason is that when carbon is priced, those emissions reductions that are least costly to implement will happen first. The IMFcalculates that countries can generate substantial fiscal revenues—revenues that would allow lower distorting taxes and new investments in the economy—by eliminating fossil fuel subsidies and levying carbon charges that capture the domestic damages caused by emissions. A tax on upstream carbon sources is one easy way to put a price on carbon emissions, although some countries may wish to use other methods, such as emissions trading schemes.

Countries that implement their INDCs through a domestic carbon price will reach their goals at lowest cost to themselves, but without global coordination on carbon prices, the cost to the world economy of whatever aggregate emissions reduction is achieved will be unnecessarily high. In order to maximize global welfare, every country’s carbon pricing should reflect not only the purely domestic damages from emissions (for example, health effects of the particulates associated with burning coal), but also the damages to foreign countries.

Setting the right carbon price will therefore efficiently align the costs paid by carbon users with the true social opportunity cost of using carbon. By raising relative demand for clean energy sources, a carbon price would also help to align the market return to clean-energy innovation with its social return, spurring the refinement of existing technologies and the development of new ones. And it would raise the demand for mitigation technologies such as carbon capture and storage, spurring their further development. If not corrected by the appropriate carbon price, low fossil fuel prices are not accurately signaling to markets the true social profitability of clean energy. While alternative estimates of the damages from carbon emissions differ, and it is especially hard to reckon the likely costs of possible catastrophic climate events, most estimates suggest substantial negative effects.

Direct subsidies to R&D have been adopted by some governments but are a poor substitute for a carbon price: they do only part of the job, leaving in place market incentives to over-use fossil fuels and thereby add to the stock of atmospheric greenhouse gases without regard to the collateral costs.

Politically, low oil prices may provide an opportune moment to eliminate subsidies and introduce carbon prices that could gradually rise over time toward efficient levels. However, it is probably unrealistic to aim for the full optimal price in one go. Global carbon pricing will have important redistributive implications, both across and within countries, and these call for gradual implementation, complemented by mitigating and adaptive measures that shield the most vulnerable.

The hope is that the success of the Paris conference opens the door to future international agreement on carbon prices. Agreement on an international carbon-price floor would be a good starting point in that process. Failure to address comprehensively the problem of greenhouse gas emissions, however, exposes all generations, present and future, to incalculable risks.

Tuesday, March 10, 2015

OxCARRE Seminar: The Grey Paradox: How fossil-fuels owners can benefit from carbon taxation

Today's OxCARRE's seminar has Renaud Coulomb from LSE (website) speaking on

The Grey Paradox: How fossil-fuels owners can benefit from carbon taxation

Abstract
This paper studies the distributional impacts of optimal carbon taxation on fossil-fuels owners. We show that optimal carbon taxation can increase the profits of owners of a carbonemitting exhaustible resource. Such phenomenon contrasts with claims from fossil-fuels owners –especially from OPEC member countries– that carbon taxation will undermine their profits. We build a theoretical model of resource extraction where a polluting exhaustible resource competes with a dirtier abundant resource and a clean backstop. The atmospheric CO2 concentration has to be kept under a carbon ceiling and the optimal extraction path is decentralized by a carbon tax. As the carbon ceiling is tightened, the exhaustible-resource rent, and thus profits, is partly captured by the tax levier (the “capture effect”), but the dirtier resource is made less competitive (the “competition effect”). We determine conditions under which profits increase as the ceiling falls. The role of resource endowments, pollution contents, extraction costs and demand elasticity is analyzed. Calibrating the model for the transportation sector, we find that limiting cumulative new emissions in this sector between 322.7 and 637.5 GtCO2 increases profits of conventional-oil owners.
Working paper available here 

Wednesday, February 25, 2015

UK considers tax decreases to support North sea oil industry

Based on a report by Oil and Gas UK, an interest representing group, that pictures a grave outlook for the industry's activities in the North Sea, the FT [here and here] and the Guardian [here] report that the government is considering corporate tax breaks for the industry in order to stimulate further investment and avoid the scrapping of new projects. Taxes went up when prices were high, taxes may go down when prices are low.

The government's main interest, supposedly, is to maximise tax revenue from oil production and use. Lowering corporate taxation now may insure that new projects are not shelved, but instead developed bringing revenues for many years. Some of the immediate revenues for the government would be given back to the industry to assure 'profitability'. If not through taxation the industry may have to find different means of cutting costs, with as ultimate measure ending production in individual
projects. The question remains whether the government would need to help with this through taxation policy or whether a future oil price increase and technological innovation triggered by hard times would take care of it. Is there really no time to wait a few quarters to see what happens with the oil price?

The call for corporate tax reductions for the oil industry stands in contrast to the calls during the past months [see earlier posts starting here] to increase consumer tax on fossil fuel use based on carbon content.  I'm speculating here, but part of the immediate tax rate decrease may actually be financed by increasing the tax on consumer use of carbon, in some revenue neutralising way of swapping consumer surplus to the oil industry. Why not?  

Wednesday, February 4, 2015

Jacques Delors (Former President of the European Commission) on a European Energy Policy.

Jacques Delors writes [energypolicyblog.com] to back a new phase in European integration focussing on energy. His letter is backed by a report [delorsinstitute.eu] written by the Jacques Delors institute.

Some quotes, my emphasis.
Making this a priority in Europe involves placing energy efficiency on an equal footing with other energy resources, and to deal with them together as part of a single energy transition. To make this happen, a decisive step must be taken towards the transition, guided by a stable and credible carbon price. The optimum instrument, in particular against the backdrop of a downward trend in oil prices, remains EU-wide carbon taxation. At the same time, subsidies for fossil fuels must be phased out as soon as possible.
Apparently aware that some major energy producers are not in the EU, he writes
Relations with immediate neighbours must be strengthened with a view to creating a pan-European area already outlined by the European Energy Community, without forgetting the Mediterranean countries. Energy relations with Norway and Switzerland must be embodied in more extensive partnerships than that of ETFA or the EEA. Similarly, relations with Russia and Turkey must be taken to a strategic level that reflects the interdependence of our respective economies rather than counting on short-term actions lacking an overall vision.
Based on the report, Switzerland is singled out for being less integrated in the EU energy market than Norway, while there may be substantial advantages in integrating in the European energy network. Turkey features as a strategic partner as a major (future) transit country for gas.

Monday, January 19, 2015

'Low oil price? increase carbon price!' 4 - The Economist edition

The Economist opens with a similar argument as the previous three posts on this topic (van Ardenne, Summers, Cochrane). However, they have a broader outlook, with different policies most advised for different parts in the world.

Due to the low oil price, which is expected to stay low for a while,
[politicians] can get rid of billions of dollars of distorting subsidies, especially for dirty fuels, whilst shifting taxes towards carbon use. A cheaper, greener and more reliable energy future could be within reach.
'Bin' the subsidies to oil companies (US) and consumers around the world (India, Indonesia, Venezuela); while taxing fossil fuels where it's not done yet (US) and integrate energy/electricity markets (EU), they recommend. In general, a complete overhole of energy policies may be needed in many countries. The low price of energy today makes it less politically daunting to actually do so.

Monday, January 12, 2015

'Low oil price? increase carbon price!' 3 - John Cochrane edition

John Cochrane responded, already a week ago, to Larry Summers op-ed on a carbon tax. He notes some comments from others and brings forth a few of his own thoughts. On of main ones is that a tax on carbon is not the only way to increase the price (so my blog series title remains valid, phew), how about a cap-and-trade, he asks.

The post pulls the idea very much into the American context. In particular, talking about a new tax breaks open the pandora box on income distribution and loopholes. The main idea of course was much generally applicable. So what is happening in other places. For instance, is there talk on further reducing the number of permits available in the European Emissions Trading Mechanism?

As a matter of fact. There is already discussion ongoing at European levels (here [ft.com], here  and here [bloomberg.com]) to reduce the number of permits in the market to increase the price, currently around €6.70 [theice.com]. In summary, these discussions were already ongoing for a while because since the great recession there is a glut of permits, in the already overwhelmed market from time that governments gave away too many credits. Some of these permits will be taken from the market, potentially to be returned in the future. The fight is going to be whether they will be. In the short term, the price of permits is expected to rise by 50-60% by June this year. I found no mention that the current oil price place a role in these decisions. As Cochrane mentions in his post, referring to the oil price of 6 months ago, as Summers did, for new policy that may take at least another 6 months to form, but likely years, is not very convincing.

Outside Europe? South Korea will start its exchange on today (12 January, here [rsc.org] and see also the second Bloomberg article above). 

Monday, January 5, 2015

'Low oil price? increase carbon price!' 2 - Lawrence Summers edition

A few weeks ago, Maria van der Hoeven, executive-director of the International Energy Agency advocated a carbon tax introduction now that oil prices are low. Lawrence Summers advocates [FT.com] the same today for the US.  

Friday, December 19, 2014

'Low oil price? increase carbon price!', Maria van der Hoeven (Exec-Dir. IEA) states

Maria van der Hoeven, executive-director of the International Energy Agency, writes in The Huffington Post and Energy Post that policy makers should take the opportunity to implement or sustain policies that encourage efficient use of fossil fuels and stimulate the case for renewables. This includes lowering subsidies in fossil fuel use, existing mostly among developing countries and increase the carbon price in developed countries, to offset the negative consequences of increased oil/gas use triggered by the low prices of today.